What is Depreciation?
5 Depreciation Calculation Methods
Depending on the assets you need to evaluate for depreciation, you can choose from five calculation methods.
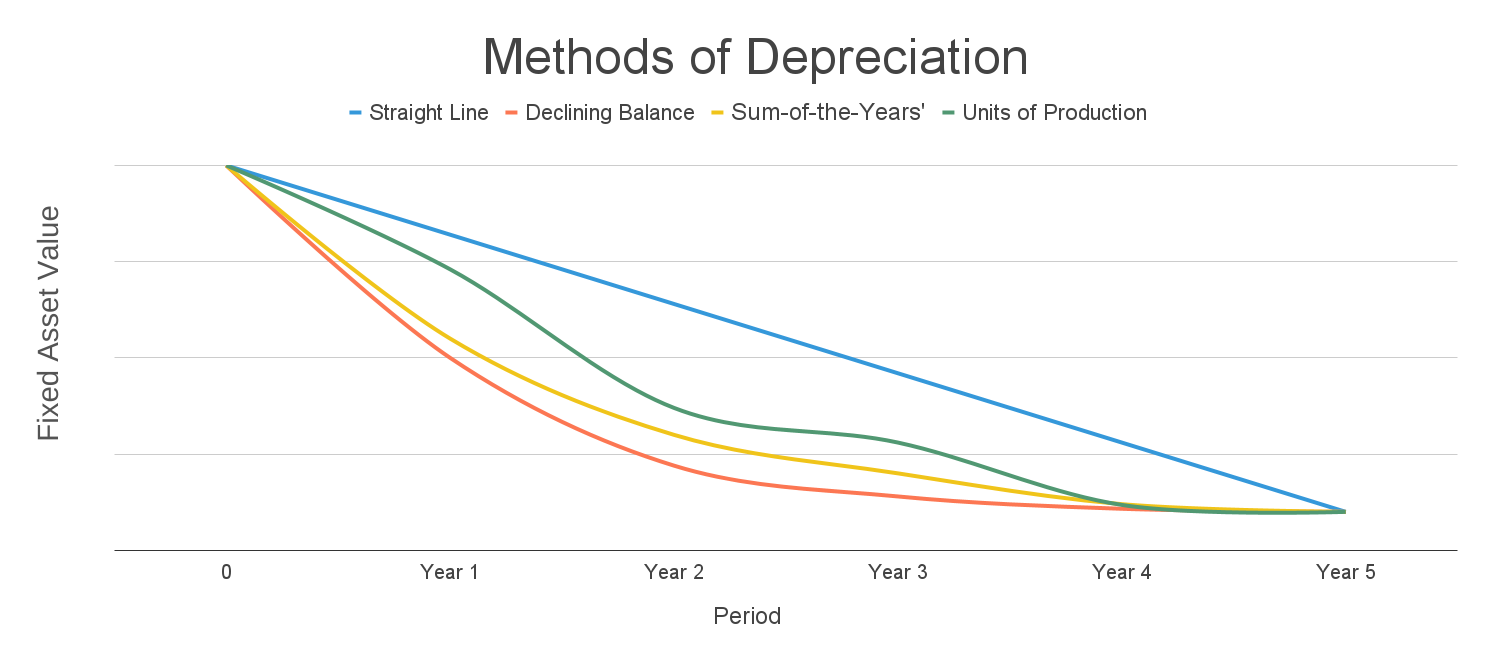
1. Straight-line Depreciation Method
2. Declining Balance Method
3. Sum-of-the-Years’ Digits Method
4. Units-of-Production Method
5. Revaluation Method
Can You Defer Depreciation?
Choosing the Correct Method
Calculating total depreciation for your tangible assets ensures accuracy on your tax returns, shows your business’s capital asset value, and maximizes asset utilization periods. Choosing a suitable method of depreciation for your assets is critical to your company’s longevity:
- Straight line: Consistent depreciation each year.
- Declining balance: Aggressive depreciation in the early years of an asset’s lifespan.
- Sum-of-the-years’ digits: Aggressive depreciation in the early years of the asset’s lifespan.
- Units-of-production: Significantly varied depreciation based on asset’s productivity.
- Revaluation: Depreciation based on the difference between the asset value assessed at the start and end of the year.
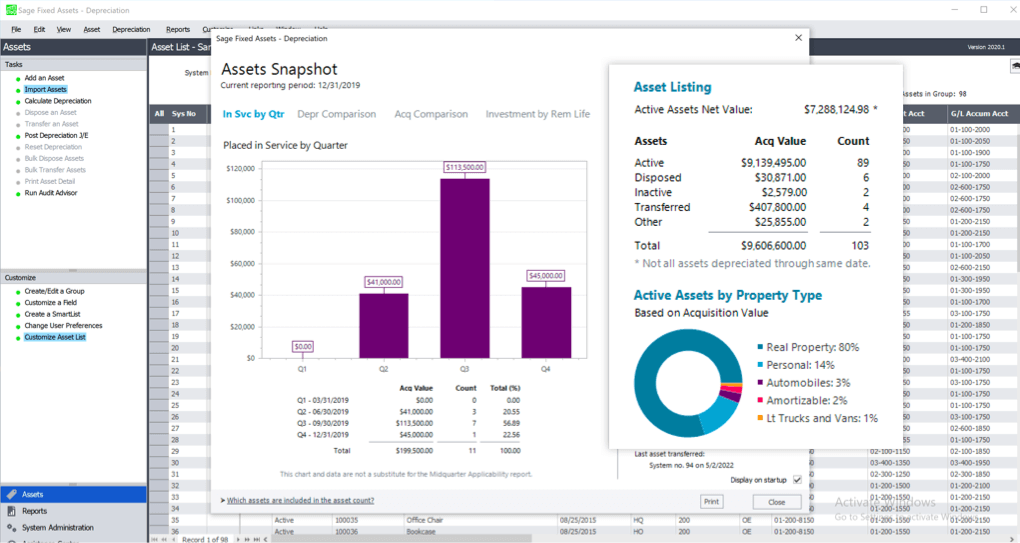
Though complex and time-consuming, these calculations are essential to your business’s financial health. In addition, you can automate fixed asset depreciation with software that tracks purchase costs, valuations, and asset gains and losses.
Frequently Asked Questions
The Internal Revenue Service (IRS) defines depreciation as an annual income tax deduction that allows a business to recoup fixed assets’ costs over time. Use IRS Form 4562 to claim depreciation deductions on your business tax return.
While certified public accountants (CPAs) and attorneys can expedite the tax return process, you are primarily responsible for the overall substantive accuracy of your return.
This tax depreciation system applies to property placed into service after 1986 and allows companies to recoup the capitalized cost of an asset over a period through annual deductions. According to Cornell Law School, the MACRS allows for greater accelerated depreciation over extended periods.
Your business logs depreciation as an expense or debit reducing income in the assets section of your balance sheet as in the following example:
Original asset price: $10,000
Less accumulated depreciation: ($4,000)
Book value: $6,000
Your income statement reports depreciation as a normal business expense, or an operating expense if the asset is used in production.
Amortization writes off the cost of an intangible asset over its useful life, while depreciation tracks loss in value for tangible assets.
Read more: Amortization vs. Depreciation